Does Homeowners Insurance Cover Garage Door Damage After a Hurricane?
In most cases, yes, a standard Florida homeowners policy typically treats a garage door as part of the dwelling structure, so wind and impact damage from a hurricane is generally covered. Coverage specifics, deductibles (including any separate hurricane deductible), and the door’s condition before the storm can all affect how a claim is handled, so confirming the exact terms with your carrier is worth doing before assuming a blanket answer applies.
What Does a Standard Policy Typically Cover?
Most homeowners policies in Florida cover wind and windborne-debris damage to the dwelling, and a garage door is generally treated as part of that structure rather than as separate personal property. That typically extends to a door that’s blown in, torn off its track, or struck by debris during a named storm.
What a policy covers and what a homeowner actually recovers after a deductible are two different numbers. Florida policies commonly carry a separate hurricane deductible that applies specifically to storm-related claims, and that deductible can be a meaningfully different amount than the homeowner’s standard deductible.
Does It Matter Whether the Door Was Already Damaged or Outdated?
Yes, and this is a detail worth understanding before a storm rather than after one. If a door was already showing significant wear, rust, or prior damage before the hurricane, an insurer may attribute some of the failure to that pre-existing condition rather than the storm itself, which can affect how the claim is settled.
This is part of why routine maintenance matters beyond just keeping the door working smoothly. A door that was in documented good condition before a storm has a clearer claim than one where the insurer can point to prior neglect as a contributing factor.
What Should You Document Before and After a Storm?
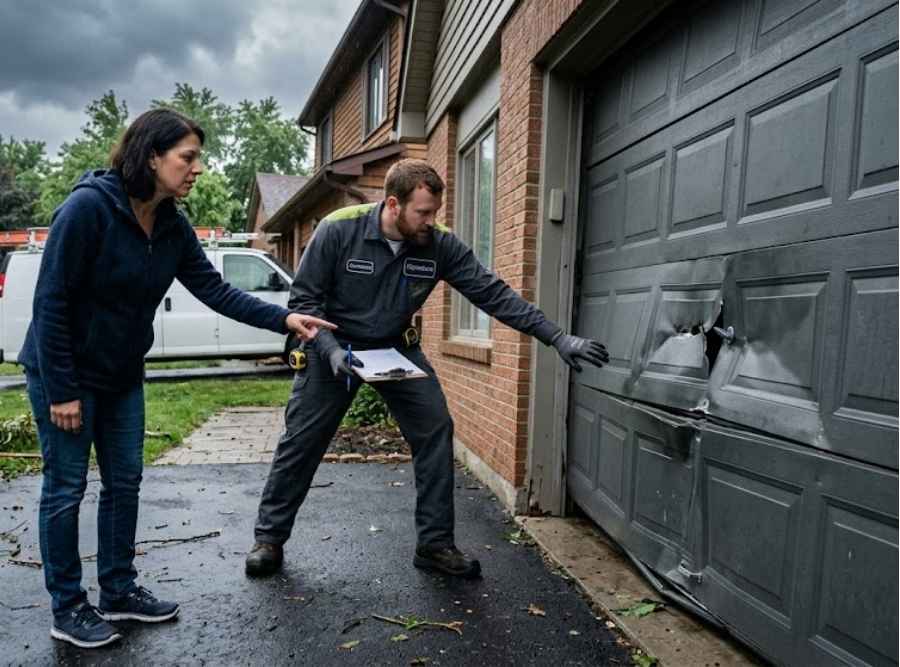
Photos of the door’s condition taken before hurricane season, and again immediately after a storm, give a homeowner something concrete to point to if a claim becomes complicated. This matters more for older or wood garage doors, where pre-existing wear can be harder to distinguish from storm damage after the fact.
Keeping records of any prior repairs, and any Florida Product Approval documentation for the door itself, also helps establish that the door met code at the time it failed, which can be relevant if the claim discussion touches on whether the door should have withstood the storm in the first place.
How Does This Connect to Wind Mitigation and Future Discounts?
A garage door replaced after storm damage is a natural point to have a wind mitigation inspection done on the new door, since the documentation needed for a future discount is the same documentation worth keeping for insurance purposes generally. Handling both at the same time, rather than treating them as separate errands, saves a homeowner from having to revisit the paperwork twice.
The Blue Steel Approach
Blue Steel Garage Door Services documents the condition and certification of a door at the time of installation or repair, which gives homeowners something concrete on file if a storm claim comes up later. That’s a small thing to ask for at the time of service, and a genuinely useful thing to have if it’s ever needed.
What to Document Before the Next Storm
Whether it’s post-storm repair or getting a damaged door properly documented and replaced, Blue Steel Garage Door Services can help make sure the paperwork holds up if it’s needed for a claim.
Frequently Asked Questions About Insurance Claims for Hurricane Garage Door Damage
Is it worth filing a claim for minor cosmetic storm damage?
That depends on the repair cost relative to the policy’s deductible. For damage that costs less to fix than the deductible, filing a claim may not make financial sense, which is a calculation worth doing before contacting the insurer.
Does the age of my garage door affect how a claim is handled?
It can. If the door was already showing significant wear or prior damage before the storm, an insurer may attribute part of the failure to that pre-existing condition rather than treating it as entirely storm-caused.
Can I choose my own contractor for storm-damage repair, or does insurance assign one?
Homeowners generally have the right to select their own licensed contractor for insurance-related repairs rather than being required to use a specific company the insurer suggests.
What should I photograph before hurricane season in case I need to file a claim later?
Clear photos of the garage door’s current condition, including any existing wear, prior repairs, or visible hardware issues, give a homeowner something concrete to reference if a claim discussion later touches on the door’s condition before the storm.
